BlogEmail
Cold email investor response rate: why nobody has a reliable number
If you've searched for a cold email investor response rate, you've probably found several confident figures, and they probably don't agree. That's not a coincidence. There's no reliable public data on reply rates for cold investor email, and anyone quoting a precise rate is guessing or describing their own users.
That line comes from the "What we don't know" section of our guide on finding investors for your startup. This post explains why the numbers don't hold up, and what you can measure instead.
Why a reliable cold email investor response rate doesn't exist
To get a trustworthy rate, you'd need a large, representative set of cold emails to investors, sent under comparable conditions, with outcomes recorded the same way. Nobody publishes that.
Here's what tends to go wrong with the figures you do see.
The sample is someone's own users
A tool, a newsletter or a consultant reports the reply rate their customers got. Those customers chose that tool, wrote emails in a particular way and targeted particular investors. Their results tell you about them, not about cold email in general.
"Reply" means different things
Does an auto-reply count? A one-line pass? Only replies that led to a meeting? Two sources using the word "reply" may be measuring different things entirely.
Fit is invisible
A rate across a mix of well-targeted and random emails says nothing about what happens when every recipient genuinely fits. And fit is the biggest thing you control.
Nobody shows their method
Most published rates come without sample size, date range or definitions. Without those, you can't tell whether a number is meaningful.
There's a quieter problem too. A published figure can anchor your expectations. If you've read that some rate is "normal" and your results look worse, you may change the wrong thing. If they look better, you may stop improving the parts that need it.
What the research does say

There is solid research on where VC deals come from, and it's worth knowing. In a survey of 885 venture capitalists at 681 firms, only about 10% of deals arrived as inbound pitches from founders (NBER Digest summary; authors' summary at Harvard Law School Forum).
Note what that is and isn't. It's a share of deals by source, not a reply rate. It covers institutional VCs, not angels, and it's from 2016, so the exact shares may have shifted. It tells you cold email is the smallest channel. It doesn't tell you what fraction of your emails will get answered.
What you can measure on your own raise
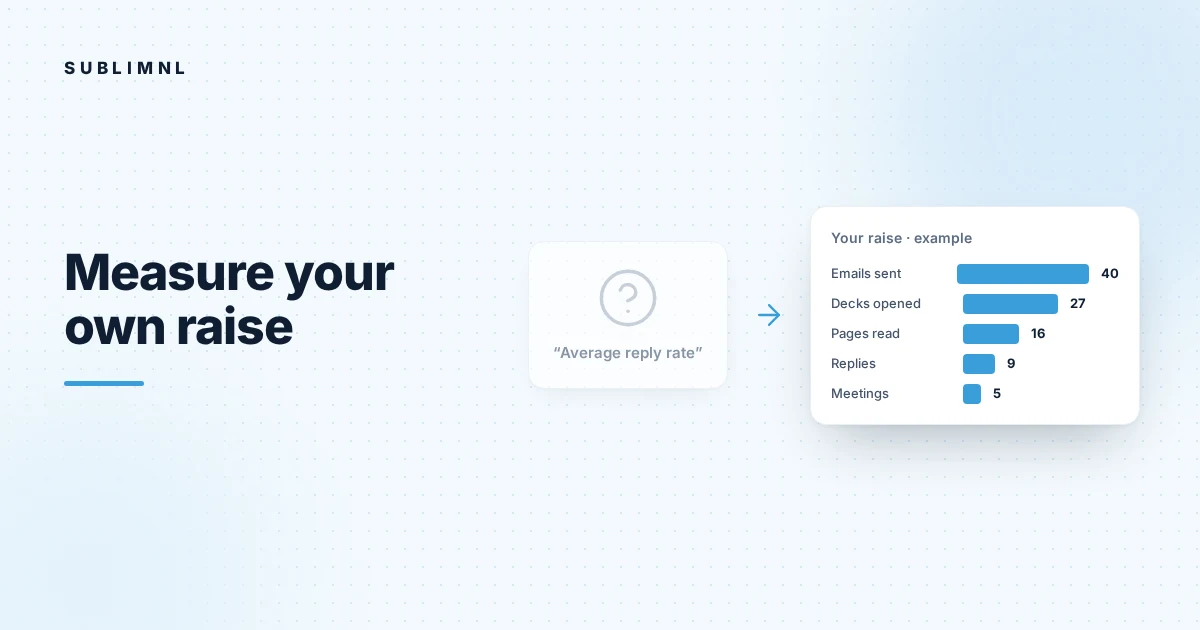
You can't benchmark against a reliable industry number. You can track your own, honestly, and learn from it during the raise.
| What to track | Why it helps |
|---|---|
| Emails sent, by tier | Separates warm, familiar and cold results |
| Opens, if you use a tracked link | Tells you whether the email reached anyone |
| How far each investor read | Shows whether the deck holds attention |
| Replies, defined your way | Write down what counts before you start |
| Meetings booked | The outcome that matters most |
| Passes, with reasons if given | Patterns point to fit or pitch problems |
Define each measure before you send, and keep the definitions fixed. That way your numbers mean something to you, even if they'd mean little to anyone else.
How to read your own results
If cold emails are opened but rarely read past the first slides, look at the deck's opening. If they're rarely opened at all, look at the subject line and whether the recipients really fit. If warm introductions convert well and cold ones don't, spend more effort finding warm paths.
Give the numbers a little time before you act on them. The first few days after a send are noisy, and a couple of quick replies or silences can look like a pattern when they aren't.
Your follow-ups also matter. Following up on what each investor actually did tends to be more useful than a fixed schedule. Our post on investor follow-up emails covers how.
What actually moves the needle
Without a trustworthy benchmark, focus on the things you can change: fit, specificity and timing. Every name should lead your stage in your sector. Every email should say why that investor in particular. And it helps when the problem you solve has been talked about before your deck arrives. Our post on cold emailing investors goes into each.
FAQ
What's a good response rate for cold emails to investors?
There's no reliable public benchmark. Track your own results by tier, define what counts as a reply before you start, and focus on fit and specificity.
Why do different sources quote different cold email reply rates?
They measure different users, define replies differently, and rarely publish their methods. That makes the numbers hard to compare and easy to misread.
Is the NBER survey a reply rate?
No. It reports where VC deals came from, with about 10% arriving as inbound founder pitches. It doesn't measure how many cold emails get answered.